Charity audit services in Surrey and beyond

We offer charity audit services for registered charities, non-profits, membership bodies, trusts and foundations.  Our charity auditors provide a range of assurance services including statutory audits, external audits and advice on how best to structure your charity. 

 With more than 50 years of experience working with charities and not-for-profits, we tailor each audit to your charity to ensure compliance, highlight improvements and deliver clear results.

Why choose our charity audit services?

  • accountants in Surrey
    Fast turnaround and minimal disruption. Your team stays focused on running the charity
  • accountants in Surrey
    Fulfil your statutory responsibilities at an affordable level
  • accountants in Surrey
    Demonstrate your credibility to donors, funders and regulators, helping you access future grants
  • accountants in Surrey
    Help you access grants and funding by meeting audit requirements and showing your charity is transparent
  • accountants in Surrey
    Protect trustees from liability by ensuring accounts are compliant, accurate and any issues are flagged early
  • accountants in Surrey
    Strengthen financial controls to use funds efficiently and lower risk by challenging current assumptions and practices
  • Untitled design (60)-1

    Reduce risk and improve performance by challenging existing assumptions and practices.

  • Untitled design (60)-1

    Use the Audit as an advisory process to look at how you can develop your charity
Our clients

Trusted by businesses and individuals across Surrey and the South East

An invaluable partner by your side
There is always someone experienced available and I would recommend them 100%


Amira Yehia Director

Proactive Approach and Clear Reporting 
During the audit process, the team's proactive approach and understandable reporting they provided us helped us gain a comprehensive perspective on the financial health of our company

Seçil Delice Erbay UK Limited

Helpful, friendly and jargon free
They are helpful, friendly and jargon free. We have much better control of the business


Trish Carver Director

Do you need an independent examination?

 If your charity is registered in the UK, trustees are legally responsible for making sure accounts are subject to the right level of external scrutiny. This depends on your charity’s income, assets, and legal form.

Where a charities gross income is less than £25,000 it is generally exempt from both audit and independent examination, unless this is specifically required by its Governing documents.

However, Trustees may still choose to have accounts independently examined or audited to demonstrate good governance, increase funder confidence, or maintain transparency.

Do you need an audit or an independent examination?

For Charities where there income is above £25,000, the external scrutiny required is as follows:

Independent Examination

Most Common


  • Required for income £25,000–£1m (assets under £3.26m)
  • Examiner must be a Fellow of the Association of Charity Independent Examiners or a member of an eligible body

Statutory audit

Full audit. 


  • Required if gross income is greater than £1 million
  • Required for gross assets of more than £3.26 million and income of more than £250,000
  • Certain charities may still need an audit, even if below these thresholds

WHY DAVID HOWARD?

We stand apart

We pride ourselves on delivering straightforward advice without the jargon. We focus on providing personalised and professional accountancy services.

  • Untitled design (60)-1

    We're transparent. We're recognised for our straightforward communication.

  • Untitled design (60)-1

    Trusted. You can rely on us for honest advice, confidentiality and reliable accountancy.

  • Untitled design (60)-1

    Comprehensive. We offer a full range of services allowing you to handle multiple matters under one roof. 

  • Untitled design (60)-1

    Free consultations. We offer a free initial consultation with no strings attached.
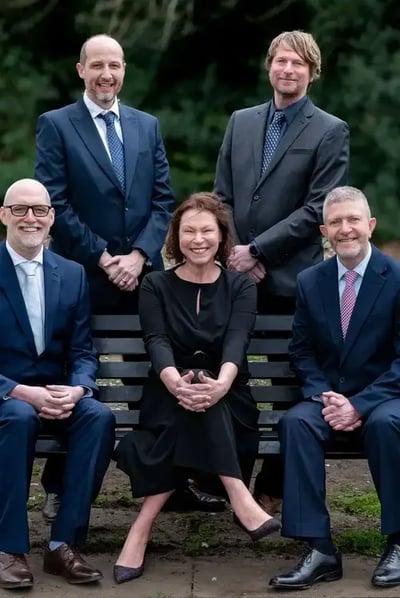
Meet your charity audit team

Our specialist charity audit team combines sector expertise with a personal, hands-on approach to help your organisation stay compliant and focused on its mission.

Outsourced bookkeeping services (1) (2)


Decades of audit experience backed by clear communication

With decades of experience, David Howard provides reliable audit services for businesses of every size. We combine technical expertise with clear communication to guide you through each stage, keeping your audit thorough, compliant and tailored to your needs.

We see our clients as partners, working through open dialogue and practical advice to deliver an audit experience that is consistent, professional, and transparent.


Speak to a charity auditor

Get clear, practical advice tailored to your situation. Speak to a Charity audit specialist

 
Add a subheading (2) (1)
4.7 Stars
Google rating
Add a subheading (2) (1)
Trusted since 1973
Over 50 years experience

Charity audit faqs

What are the audit requirements for UK charities?

UK charities in England and Wales must have a statutory audit if gross annual income exceeds £1.5 million, or if gross income exceeds £500,000 and gross assets exceed £5 million.

These thresholds apply to financial years ending on or after 30 September 2026. A charity may also need an audit under company law or other applicable requirements.

The thresholds are not the same across every UK nation. Scotland and Northern Ireland have separate regulatory rules. In England and Wales, charities below the statutory audit thresholds can generally choose an independent examination instead, subject to their legal structure, governing document and funding agreements.

What are the Charity Commission regulations on audit thresholds?

For charities registered in England and Wales, the Charity Commission's statutory audit thresholds are gross annual income above £1.5 million, or gross income above £500,000 combined with gross assets above £5 million. The rules apply to financial years ending on or after 30 September 2026.

A statutory audit is also required where the charity must prepare audited group accounts. The Charity Commission can require an audit in certain cases involving suspected misconduct or mismanagement. Charitable companies must also check whether company law requires an audit.
For financial years ending before 30 September 2026, the general thresholds were income above £1 million, or income above £250,000 combined with gross assets above £3.26 million. Trustees must use the thresholds for the correct financial year.

How to choose an audit firm experienced with non-profits?

Choose an audit firm that has audited charities of a similar size and type, understands charity-specific accounting rules and can demonstrate experience with your charity's funding and reporting requirements. For a statutory audit, the firm must also be authorised to conduct audits.

Ask prospective firms about their experience with charities that receive similar types of income, such as grants, donations, legacies or trading income. Check that the proposed team understands restricted and unrestricted funds, the Charities SORP and any relevant group-accounting requirements.

Before appointing a firm, compare its proposed audit team, scope of work, timetable, communication arrangements and fees. Ask how it will raise issues with trustees and explain recommendations. Relevant experience among the people carrying out the audit matters more than a broad claim to specialise in the charity sector.

How long do charity audits usually take?

A charity audit typically takes four to eight weeks from the start of audit fieldwork to completion, provided the accounts and supporting records are ready. Larger or more complex charities may need longer, particularly if they have multiple funding streams, subsidiaries, incomplete records or delays responding to audit queries.

The process usually includes planning, testing financial transactions and balances, resolving queries, discussing adjustments and issuing the audit report. The overall timetable also needs to allow for preparing the accounts before fieldwork and obtaining trustee approval afterwards.

To reduce delays, prepare reconciled accounts, organise grant agreements and supporting evidence, maintain clear records of restricted funds, and nominate someone to coordinate responses to the auditor. Charities should plan around their accounts filing deadline, not just the estimated audit period.

How to find a qualified accountant for a charity audit?

Start by searching the Register of Statutory Auditors to find firms authorised to carry out statutory audits. You can also use the ICAEW directory

Shortlist firms that audit charities and have experience with organisations of a similar size, funding structure and activities. Then compare their charity accounting expertise, proposed audit team, fees and availability.

When assessing shortlisted firms, check that they:

  • Have relevant charity experience: Ask whether they audit charities similar to yours and understand the issues affecting your organisation.
  • Understand charity accounting: Look for knowledge of the Charities SORP, restricted funds, grants, donations and charity reporting requirements.
  • Have an experienced audit team: Find out who will lead the audit and who will carry out the day-to-day work.
  • Offer a clear timetable: Confirm when they can start, what records they need and when they expect to complete the audit.
  • Provide transparent fees: Request a written proposal detailing the audit scope, what is included and any potential additional charges.

Before appointing a firm, ask for examples of its relevant charity audit experience and references where available. Compare the proposed work, expertise and communication arrangements, not just the quoted price.

A general accountancy qualification does not automatically authorise an accountant to conduct a statutory audit.